
[ad_1]
The euro zone government’s borrowing costs have risen again, testing the nervousness of European Central Bank policymakers before deciding whether to slow down asset purchase decisions from next month.
If the ECB at its next board meeting on June 10 does reduce its bond purchases from the recent net purchases of more than 80 billion euros per month, it will work with other central banks that have already done so to cope with changes. Good situation. Economic prospects, including Canada and the United Kingdom.
Fed officials have Discussed Whether to start talking about reducing its bond purchases at the meeting in late April.
However, the recent rise in bond yields underscores how cautious it will be if the European Central Bank wants to avoid unwelcome increases in financing costs in countries with weak bloc economies.
Last Friday, European Central Bank President Christine Lagarde (Christine Lagarde) said in response to a question about whether the European Central Bank will slow down its bond purchases. Issues for debate”.
Lagarde added: “I’ve said repeatedly that policymakers need to build the right bridge between the pandemic until it enters the recovery phase so that we can actually perform our tasks. This is what we will do.”
The withdrawal of monetary stimulus after the crisis is a balancing act. Doing so too quickly will scare investors and put the recovery in danger. But this is too slow, and the economy may overheat, which makes tightening policies even more painful in the future.
Paul Diggle, deputy chief economist of Aberdeen Standard Investments, said: “This is a trick of a magician.” “If Lagarde can manage communication in a very safe way , Then maybe she can avoid this gradual reduction and deepening the sell-off.”
The more conservative “hawks” on the ECB Council have been working hard for several weeks, hoping Slow down Bond purchases, thinking that the growth and inflation outlook may be justified, this is likely to be reflected in the central bank’s latest forecast next month.
But there are more “paranoid” board members PostponeCall on the European Central Bank to maintain stimulus measures at least until the economy fully recovers from the pandemic, and the inflation rate continues to rise, in line with its goals.
A council member said that the ECB is unlikely to slow down its bond purchases because investors overreacted to concerns about rising inflation. The central bank believes this is only temporary, adding: “We don’t want to send inflation signals through Signals to encourage this practice. The pace of purchases is decreasing.”
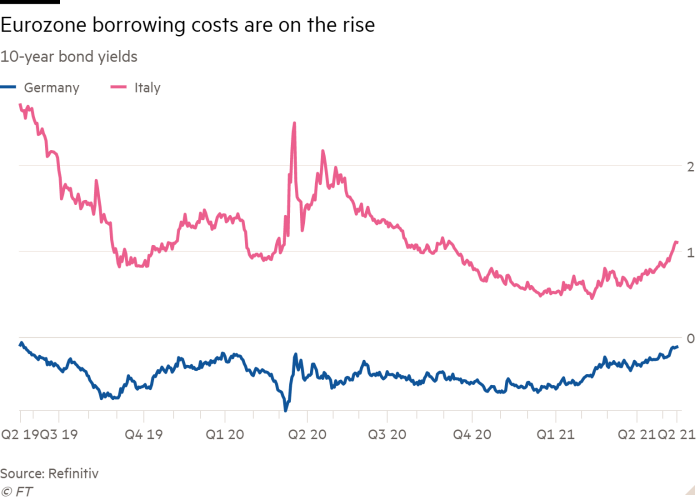
The European Central Bank’s decision has been complicated by the recent drop in government bond prices, which has raised the GDP-weighted average of 10-year government bonds in the Eurozone to 0.27%, the highest level since June last year.
This move is partly due to German borrowing costs Since the beginning of the year, benchmarks in the rest of the euro zone have fallen from very low levels, because investors have responded to improved prospects.
The yield on Germany’s 10-year government bond was relatively high on Friday, at -0.12%. Goldman Sachs analysts predict that the rate of return will turn positive later this year.
The challenge for the European Central Bank is that it will work to maintain “favorable financing conditions”-preventing households, businesses, and governments from borrowing costs faster than the economic recovery.
The European Central Bank’s response to the most recent surge in euro zone bond yields at the beginning of this year was a pledge to purchase bonds at a “significantly higher rate” in the second quarter.
But at that time, the euro zone was still under pressure from the coronavirus containment measures. The central bank regarded the rise in bond yields as an unprovoked spillover from the United States. Due to the 19,000-ton fiscal stimulus plan, the recovery of bonds was faster.
Investors now believe that the European bond market is being driven by more real signs of recovery. Mohammed Kazmi, investment manager of Union Bancaire Privée, said: “Since the beginning of the year, the outlook for the euro zone has been quite pessimistic.” “Now with the acceleration of the vaccine program, we are seeing some optimism that is already priced in the United States.”
Bright growth prospects have weakened the attractiveness of ultra-safe assets such as German government bonds. Inflation expectations at home and abroad have also increased.
Germany’s 10-year break-even rate is a market-based indicator of inflation expectations, at 1.41%, which is higher than the less than 1% earlier this year. Although this is still well below the European Central Bank’s target of slightly less than 2%, it means that despite the bond market’s sell-off, the inflation-adjusted real yield remains flat.
Unhedged-markets, finances and strong opinions
Robert Armstrong analyzed the most important market trends and discussed how the smartest people on Wall Street responded to these trends.registered Here Make press releases sent directly to your inbox every business day
Allianz economist Katharina Utermöhl said that higher inflation expectations make it more likely that the European Central Bank will slow down bond purchases to between the first and second quarters. “Slightly loosened” and added that it became a “communication challenge.”
The risk is that the European Central Bank may accelerate the recent rise in borrowing costs for weak, debt-laden economies-the so-called peripheral countries of the euro zone. Italy’s 10-year government bond yield reached an eight-month high of 1.16% on Wednesday. Compared with the 10-year debt of Berlin, Rome’s extra income or spread is the highest since January.
Frederik Ducrozet, a strategist at Pictet Wealth Management, said: “Hawks can easily say that this is all part of a healthy recovery in inflation expectations, and the absolute level of returns is still very low.” “But when it comes to the risks of economic recovery, you have to consider the external spreads.”
[ad_2]
Source link