
[ad_1]
This article is the live version of the unhedged newsletter.registered Here Make press releases sent directly to your inbox every business day
This is the end of Unhedged’s first week. How’s it going? Email me: Robert Armstrong@ft.com.
Quantitative Easing Policy and Stock Prices (Part Two)
These are two lines, mostly at the top right:
M2’s money supply (cash, deposits, money market accounts) and S&P 500 are two lines. Due to quantitative easing, M2 has grown rapidly: The Fed buys securities with cash, thereby putting new funds there. The reason why the S&P rose rapidly is unclear.The fact that the two routes came together recently has inspired a popular causality: “The Federal Reserve is printing money. It must go somewhere and then enter the stock market.” A few days ago I famous These causal stories are wrong because cash is not converted into stocks. When I buy stocks, the seller gets cash. It is not “in the stock market.”
What really happened is that compared with stocks, the loss of all excess funds reduced people’s demand for it, and the increase in relative demand for stocks forced the stock price to rise. This is how quantitative easing affects stock prices (or one of its ways; others, especially central bank governors, prefer reports that quantitative easing reduces discount rates, and this statement will appear soon.)
Eric Barthalon, the global head of Allianz Capital Markets Research, points out that this process is self-limiting. As the stock price rises, the weight of the cash relative to the stock in the investor’s portfolio drops to a level that is satisfactory to the investor. Investors stopped too many transactions and the price stabilized. In this story, it’s not that the Fed is just flooding the market with cash. There is an intermediary factor: investors prefer cash relatively.
Barthalon’s argument (which I find very persuasive) is: (a) investors’ preference for cash is unstable, and (b) the Fed cannot control cash at important moments (that is, when the market is falling). You can track investors’ unstable preference for cash by looking at the speed of currency flow or the degree of change of hands. Baltharon told me:
“It is not the quantity of money that causes the price of money to rise or fall, but the amount of money in circulation… Historical experience tells us that the central bank cannot control the speed of currency circulation, especially in the capital market.”
Now we know why central banks may prefer the idea of quantitative easing, that is, they control the discount rate that determines the value of stocks by keeping government bond yields low. Because theoretically, even if investors suddenly decide that they like cash very much, the leverage is still effective, and they will do so when the market drops.
This is a long-term chart of Barthalon’s stock market currency velocity (daily market transaction value divided by M2) and stock market value. Look at how the speed drops sharply when the market drops:
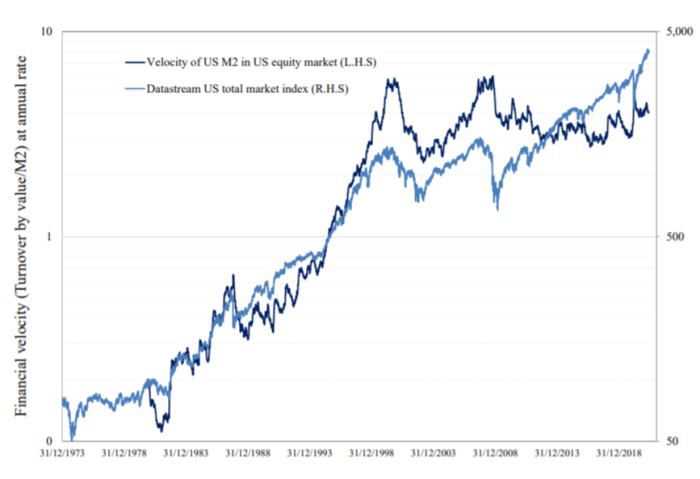
These two lines are different and are related to a neat cause and effect story. The conclusion is that a large amount of money alone cannot keep the stock market high.
Armstrong was wrong: Bitcoin
Yesterday I argued that it is better to treat Bitcoin as an equity in a company whose only asset is unverified technology. When Bitcoin becomes money, the technology will be proven. However, Bitcoin is no longer money, because when people make transactions, it is not widely accepted as a payment method, where transactions are few, transaction costs are high, and so on.
The most common response I received is that Bitcoin is not meant to make money. Money has two key characteristics. It is a medium of value storage and communication. Most people who think I am wrong think that Bitcoin is nothing more than stored value. This is why its limited supply is so important. If transaction costs are high, liquidity is insufficient, etc., then who cares. It is similar to gold and diamonds. The distinguishing feature of these commodities is rarity and preciousness, rather than ease of use.
I was not convinced. Gold and diamonds are used in industry and jewelry, and they have thousands of years of practice to support their preciousness. The only thing that supports Bitcoin as a store of value and a precious commodity is that it can be both a store of value and a store of value. especially A good medium of exchange-a medium that allows low-cost, wide-ranging and frictionless transactions. This is the real key without the need for third-party supervision or government control. And I don’t think we know this is the case yet. Bitcoin is scarce, but so are the watercolors I painted in high school. But this does not make them a store of value.
Similarly, the person in charge of Bitcoin should sign up for #fintechFT, our newsletter on the intersection of technology and finance.Click on Here.
A good book
I was moved This Bloomberg’s story about such strong demand for U.S. homes is that home builders are moving away from fixed prices and conducting blind auctions to ensure the highest bids:
“The collision of forces related to the pandemic [is] Only keep new inventory when you need it most. Buyers are stamping new homes because remote jobs will destroy employment, while soaring timber costs and shortage of workers are delaying construction. “
This description shows that there is no 2007-style toxic speculation in this combination. This makes me very paranoid. Isn’t there speculation everywhere these days? Why not housing? I don’t know if there is any evidence, but I want to look for it. If so, email me.
[ad_2]
Source link